Out-of-state buyers moving to Greater Fort Lauderdale need to plan beyond the list price, insurance quotes, flood zones, property taxes, HOA rules, and local market timing all shape what you can actually afford and where you’ll be happy living.
What do out-of-state buyers need to know before relocating to Fort Lauderdale?
Out-of-state buyers relocating to Greater Fort Lauderdale need to plan around more than the purchase price. Insurance premiums, flood-zone designations, property taxes, HOA rules, and Florida residency logistics can all affect your budget and timeline as much as the home itself. Getting pre-approved and lining up a local agent, lender, and insurance contact before you start touring is the move that separates smooth relocations from expensive surprises.
Key Takeaways
- Broward County single-family homes had a median sale price of $650,000 in July 2026, up 4.84% year over year, according to MIAMI REALTORS® data.
- With roughly 4.5 months of supply for single-family homes in Broward County as of July 2026, conditions lean seller-side, but city-level data shows homes selling around 4% below asking on average, so negotiation is still on the table.
- Insurance is an affordability filter, not an afterthought, get quotes before you make an offer, especially on pre-2002 construction or canal-adjacent properties.
- Florida’s Homestead Exemption can reduce your taxable value after you establish primary residency, but your tax bill will differ from the current owner’s, check Broward County Property Appraiser records for every property you seriously consider.
- Recent local market data for Oakland Park shows a median sale price of $409,000 and a median of 38 days on market, with 329 active listings, one of several entry points for buyers priced out of the beach-adjacent submarkets.
What does the Fort Lauderdale market actually look like for buyers right now?
Here’s the honest picture heading into fall 2026: this is not a frenzy, and it’s not a fire sale. It’s a negotiable but competitive market, and the data backs that up.
According to Lamacchia Realty’s 2026 Broward County Mid-Year Review, home sales through mid-year 2026 are up 4.5% compared to the same period in 2025, average prices are up 6.4%, and the number of homes listed is down about 10%. Fewer listings and more buyers means competition for the right properties, but it doesn’t mean sellers hold all the cards.
MIAMI REALTORS® data reported by local brokers puts Broward County’s single-family median sale price at $650,000 in July 2026, up 4.84% from July 2025. The condo and townhouse median came in at $255,000 for July 2026, down slightly from the prior year, so attached housing is running softer than detached right now. Months of supply for single-family homes sat at roughly 4.5 in July 2026, which technically still favors sellers (a balanced market is closer to 5-6 months).
City-level data from Realtor.com’s Fort Lauderdale market report for August 2026 tells a slightly different story at the street level: median days on market around 86 days, and a sale-to-list ratio near 96%, meaning homes sold roughly 4% below asking on average. That’s real negotiating room if you know how to use it.
One more data point worth knowing: recent local market data for Oakland Park shows a median sale price of $409,000 and 38 median days on market, with 329 active listings and 90 new listings in the past 30 days. For buyers who need to stretch their budget, Oakland Park and Pompano Beach offer meaningful entry points compared to the beach-adjacent submarkets.
Here’s a quick look at how several Greater Fort Lauderdale areas compare right now:
| Area | Median Sale Price | Median Days on Market |
|---|---|---|
| Pompano Beach | $355,000 | 24 |
| Lighthouse Point | $703,000 | 53 |
| Victoria Park | $907,500 | 56 |
| Las Olas Isles | $4,853,000 | 46 |
| Poinsettia Heights | $667,000 | 46 |
Source: Aggregated public listing data, trailing ~90 days, as of September 2026. Area-level medians, an individual home’s value varies by condition, street, and build year.
One thing I tell every relocating buyer I work with: don’t time your move around the calendar. South Florida markets often feel busier in winter and early spring when seasonal residents are here, but the 2026 mid-year numbers show the market stayed active well into summer. Watch current data, not national headlines.
For a deeper look at how out-of-state and snowbird buyers fit into the Fort Lauderdale market cycle, I put together a post on snowbird buyers and South Florida relocation timing that covers the seasonal dynamics in more detail.
Where do you want to actually live? The neighborhood trade-off no one tells you about
This is the question that matters most, and it’s the one out-of-state buyers usually get wrong because they’re comparing to their last city instead of thinking through how they’ll actually spend their days here.
The east-of-I-95 neighborhoods, Victoria Park, Las Olas Isles, Coral Ridge, Rio Vista, offer walkability, proximity to the beach and downtown restaurants, and a genuinely urban feel by Florida standards. You’re trading lot size and square footage for lifestyle. These segments have held their values through mid-2026 even as some west-of-I-95 single-family pricing has shown slight softness. If you’re coming from a dense city and want to keep that energy, this is where you find it, at a price per square foot that reflects it.
If you need more space, a yard, or want a specific school zone, the suburbs west of I-95, Plantation, Cooper City, and similar communities, give you more home for the money and larger lots. You’ll drive more. That’s the trade-off, and it’s real. I always encourage buyers to spend time in both environments before deciding, because what sounds appealing in a description sometimes feels very different on a Tuesday afternoon.
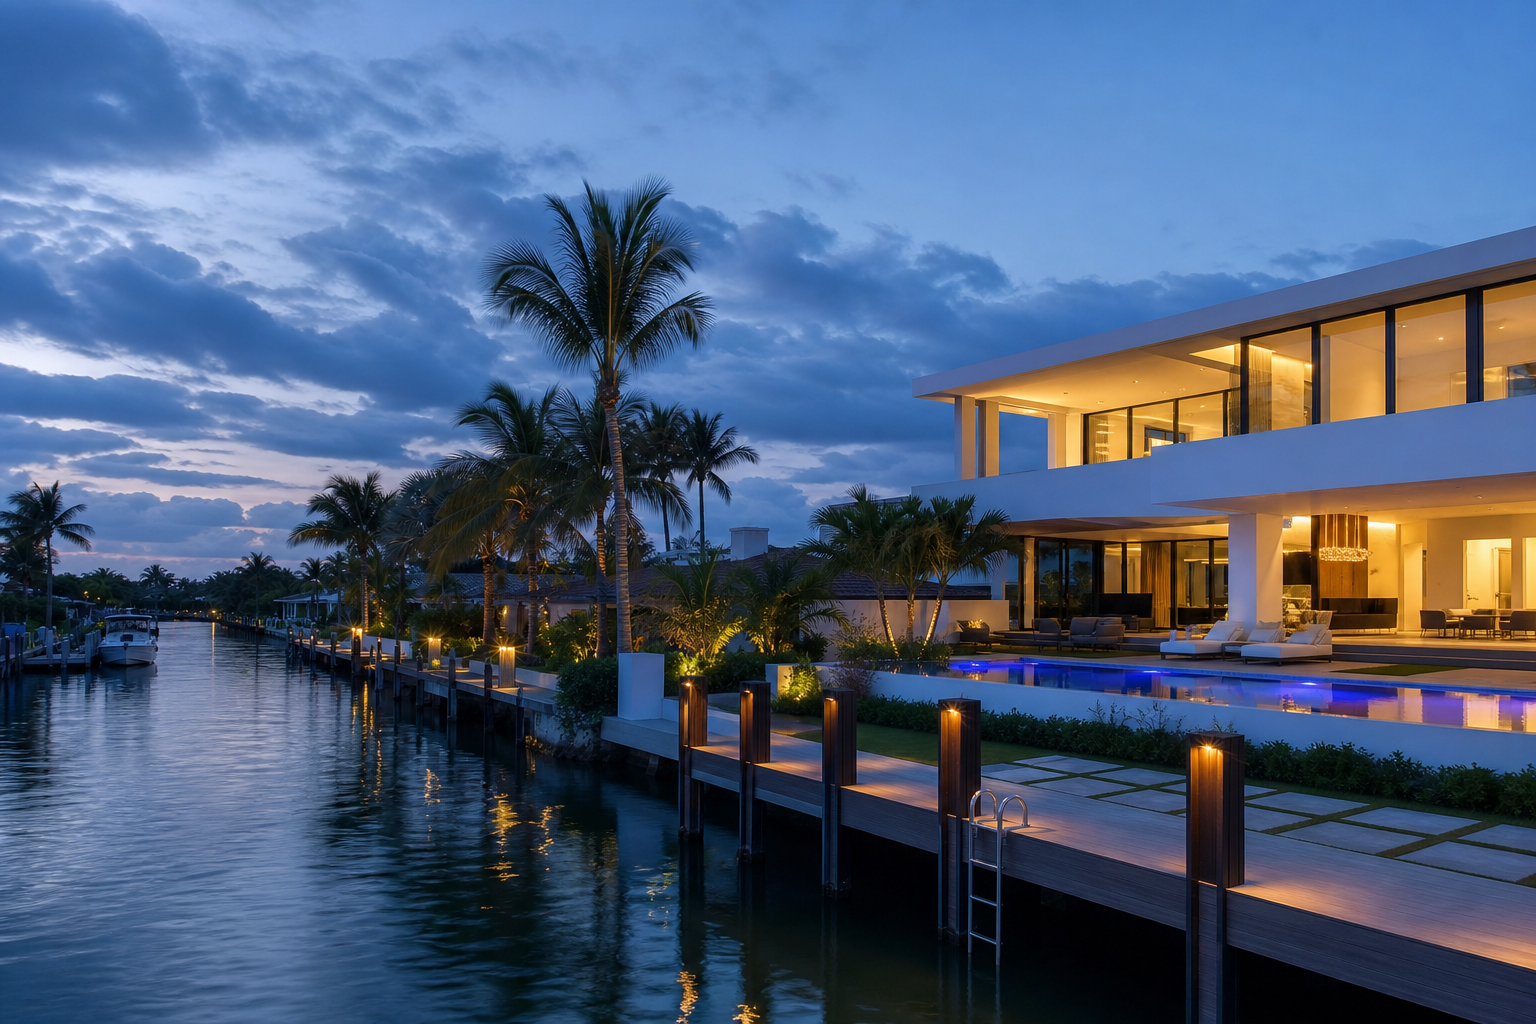
Waterfront and beachfront properties are their own category. The luxury east-of-I-95 waterfront market has stayed firm through the first half of 2026, but these homes carry additional due-diligence requirements that inland buyers don’t face: seawall and dock inspections, wind mitigation reports, flood-zone verification, and insurance quotes that can genuinely change your affordability picture. I walk every waterfront buyer through that checklist before we get serious about any offer.
What costs do out-of-state buyers miss when budgeting for a Fort Lauderdale home?
The list price is the easy part. Here’s what catches out-of-state buyers off guard.
Insurance: get your quotes before you make an offer
Florida’s insurance landscape is unlike anywhere else in the country, and it’s the single biggest budget variable I see relocating buyers underestimate. Homeowner’s insurance, windstorm coverage, and flood insurance are three separate considerations, and the premium for each can vary dramatically depending on the home’s age, roof type, impact windows, elevation certificate, and proximity to water.
Homes built before 2002 and properties near canals or the waterfront deserve extra attention here. I strongly recommend getting insurance quotes early in your search, before you’re emotionally committed to a specific property, because a premium that doesn’t fit your budget is a reason to walk away, and you want to know that before you’re under contract. Local relocation guides and South FL Insider’s relocation resources consistently flag this as a central affordability filter, not a line item to figure out at closing.
Check FEMA’s Flood Map Service Center for any property you’re seriously considering. Your lender will require flood insurance if the home is in a designated flood zone, but even properties outside mandatory zones can carry meaningful flood risk in South Florida’s flat terrain and canal-heavy neighborhoods.
Property taxes and the Homestead Exemption
Before you rely on the current owner’s tax bill as a guide to your future costs, check the Broward County Property Appraiser’s records for the property’s assessed value and tax history. When a home sells, the assessed value can reset, and your tax bill may differ significantly from what the seller has been paying, especially if they’ve owned the home for years and benefited from Florida’s Save Our Homes cap on assessment increases.
Once you establish primary residency in Florida, you can apply for the Florida Homestead Exemption, which reduces the taxable value of your primary residence. But that benefit kicks in after you’ve moved in and filed, it doesn’t apply at closing. Plan your budget around the pre-exemption tax figure first, then treat the exemption savings as a bonus once it’s in place. For more on how the Save Our Homes cap and portability work if you’re also selling a Florida property, my post on Florida’s Save Our Homes portability breaks that down in detail.
HOA and condo fees: read the documents, not just the monthly number
Out-of-state buyers, especially those coming from markets where HOAs are less common or less regulated, often focus on the monthly fee and miss everything else. In South Florida condos and planned communities, you need to review the full association documents during due diligence: pending special assessments, reserve fund health, building rules around move-in scheduling, elevator reservations, parking, and approval processes.
Many Fort Lauderdale condo buildings have specific move-in windows, scheduled elevator time, required deposits, and restrictions on when long-distance movers can arrive. If you’re coordinating a cross-country move, plan your moving timeline around the building’s rules, not just your preferred date. This is one of those logistics details that blindsides people who’ve never dealt with a South Florida condo association before.
Inspections and maintenance: South Florida is different
A thorough inspection in this market covers roofs, electrical systems, plumbing, windows, seawalls, and docks, and the stakes are higher than in milder climates because hurricane exposure, salt air, and year-round humidity accelerate wear in ways that buyers from the Northeast or Midwest simply haven’t dealt with. Budget for a more comprehensive inspection scope than you might be used to, and expect a different maintenance rhythm once you’re settled: hurricane prep, regular AC servicing, and pest control are part of life here, not exceptions.
What logistics do you need to handle after you move to Florida?
The transaction closes, the movers leave, and now the administrative side of becoming a Florida resident begins. I call it the “paperwork week,” and planning for it ahead of time makes the whole transition smoother.
Florida law requires new residents to obtain a Florida driver’s license and register their vehicles after establishing residency. The Florida Department of Highway Safety and Motor Vehicles handles both. Get this done promptly, it’s also a prerequisite for filing your Homestead Exemption application with the Broward County Property Appraiser.
On the school front: if school zoning matters to your decision, verify the specific assignment for each property address directly through Broward County Public Schools. Neighborhood names and third-party maps are not reliable for this, the district’s address-based lookup is the only source that counts. This is especially important in areas where school boundaries don’t follow neighborhood lines cleanly.
For commuting, it’s worth knowing whether proximity to the Brightline rail stations matters to your daily life. If you’ll commute between Fort Lauderdale, Miami, or West Palm Beach, being within reasonable distance of a Brightline stop changes the calculus on where to live. It won’t replace a car in most of South Florida, but it can meaningfully reduce how much you’re driving.
Finally, work with a Florida-based lender if you can. Local lenders understand the insurance, flood-zone, and condo/HOA nuances that out-of-state lenders often don’t, and those details affect your pre-approval, your loan type, and your ability to close on certain properties. An out-of-state lender who’s never dealt with a South Florida condo association’s approval process can create real delays.
Frequently Asked Questions
Is Fort Lauderdale still a seller’s market in mid-2026, or has it cooled enough for buyers to negotiate?
It’s technically still a seller’s market, but with meaningful room to negotiate. MIAMI REALTORS® data shows roughly 4.5 months of supply for Broward County single-family homes in July 2026, which leans seller-side, but city-level data from August 2026 shows homes selling around 4% below asking on average and sitting on the market for around 86 days. That’s not a frenzy. Buyers who are prepared and working with a local agent are finding real negotiating opportunities, particularly on properties that have been sitting.
How do I factor South Florida insurance costs into my home-buying budget before I move?
Get insurance quotes as early in your search as possible, ideally before you’re emotionally committed to a specific property. Premiums in South Florida vary significantly based on the home’s age, roof type, impact windows, elevation, and proximity to water or canals. Treat insurance as an affordability filter the same way you’d treat the list price: if the combined cost of homeowner’s, windstorm, and flood coverage doesn’t fit your budget, that’s a reason to move on. A local insurance agent who works with South Florida properties regularly can turn around quotes quickly once you have a specific address.
How do I check flood zones and hurricane risk for specific homes in Greater Fort Lauderdale?
Start with FEMA’s Flood Map Service Center, which lets you look up any property’s flood-zone designation by address. Canal-adjacent and coastal properties carry the most exposure, and homes built before 2002 often lack the construction standards that newer builds have for wind resistance. Beyond the FEMA map, ask for the property’s elevation certificate if one exists, and factor flood-zone designation into your insurance quote conversations early, your lender will require flood insurance if the home is in a designated zone, and the premium is part of your real monthly cost.
How does the Florida Homestead Exemption work for someone buying their first home in Broward County?
The Florida Homestead Exemption reduces the taxable value of your primary residence after you establish legal residency and file an application with the Broward County Property Appraiser. It doesn’t apply at the time of purchase, you apply after you’ve moved in and established Florida as your primary residence. The important thing to understand as a buyer is that the current owner’s tax bill may not reflect what you’ll pay: when a home sells, the assessed value can reset, and you’ll want to review the property’s assessment history before closing to understand your likely tax exposure in year one.
What should I look for in Fort Lauderdale condos or HOAs as an out-of-state buyer?
Review the full association documents during your due-diligence period, not just the monthly fee. Key items include pending special assessments, the reserve fund’s financial health, rules around move-in scheduling (many buildings require reserved elevator time and restrict moving hours), parking, and any buyer approval process the association requires. Out-of-state buyers coordinating long-distance moves need to plan their moving timeline around the building’s rules, a building that only allows moves on weekdays between 9am and 4pm can create real logistics problems if you haven’t planned for it.
Buying a home from out of state is manageable when you have the right team and the right plan. The buyers who struggle are the ones who treat it like a local purchase and skip the steps that only matter in South Florida. The ones who do it well come in prepared, get their insurance quotes early, understand the tax picture, and work with people who know this market from the inside.
If you’re planning a move to Greater Fort Lauderdale and want to walk through what the process looks like for your specific situation, I’m happy to spend some time on it. Book a conversation with me here and we’ll start with what actually matters for where you’re coming from and what you’re looking for.
Equal Housing Opportunity. Scott Morreau, P.A., Broker Associate, Real Broker, LLC (Licensed since 2001), regulated by the Florida Real Estate Commission. This article is general information only and is not legal, tax, or financial advice. Confirm your specific numbers with your title company, tax advisor, or lender. Real Broker, LLC main office: 8291 Championsgate Blvd., Championsgate, FL 33896. Scott’s office at 2312 Wilton Drive is not a registered branch office and is not open to the public; meetings by appointment only.